Stranded or Reborn: Why Beijing's 1990s Trophy Towers Deserve a Second Look
Photo: Chris Downer, CC BY-SA 2.0, via Wikimedia Commons
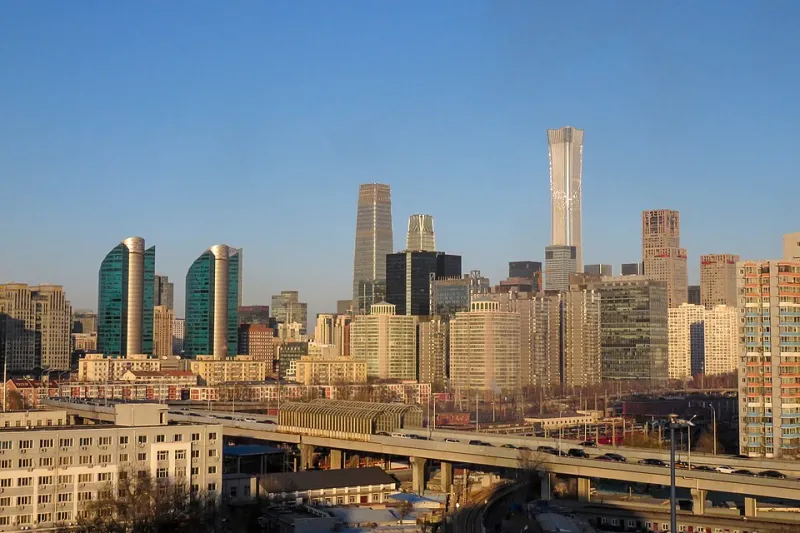
Walk into a late-1990s tower on the eastern edge of Chaoyang and the diagnosis writes itself. Polished granite that has been polished too many times. A lobby that once signaled arrival and now signals a different decade. And, two floors below grade, a chiller plant running at an efficiency that would make an engineer wince.
The instinct among cross-border buyers is to pass. The instinct is wrong — or at least premature. For family capital with a ten-year horizon and the patience to fund capital expenditure, Beijing's older prime stock is where the more interesting risk-adjusted math currently sits.
The New-Build Bias
Institutional flows favor new product for defensible reasons: cleaner documentation, simpler certification narratives, brand-new warranties, and an exit story that a committee can approve in one meeting. Family offices, however, are not committees. They are not marking to market quarterly, they are not hostage to a fund life, and they do not need a building that photographs well for an offering memorandum. They need income, durability, and an entry price that leaves room for error.
That mismatch is the opportunity. The green premium in Beijing has become well understood at the top of the new-build market. It is far less well priced in the existing stock, where buyers still discount for age without adjusting for what a disciplined retrofit can achieve.
What the Older Stock Actually Offers
Four attributes recur in the 1990s and 2000s cohort. Location that cannot be replicated — these buildings were built when the best sites were still available. Floorplates sized for real organizations, not optimized for a yield model. In-place income while the retrofit is executed in phases, which is the difference between a project and a bet. And a tenant base that has already chosen the district, meaning renewal conversations start from familiarity rather than from a leasing tour.
There is also a softer asset. Buildings of this era were often over-engineered structurally. That redundancy is what makes deep intervention possible: added plant, upgraded risers, expanded fresh-air capacity.
The Arithmetic of the Premium
A deep retrofit — envelope, glazing, ventilation, controls, lighting, and where feasible electrification of heating — typically targets a 25 to 40 percent reduction in energy use intensity. In Beijing's prime segment, that translates into three distinct returns: operating cost reduction that flows to net operating income; a rental uplift once operational certification is achieved, because tenants with global sustainability mandates can now sign; and, at exit, access to a buyer universe that will not underwrite an uncertified asset at any price it likes.
The third is the one that matters most and is the least modeled. Certification is increasingly a liquidity feature, not a marketing feature.
Tailwinds That Are Not Marketing
Beijing's regulatory direction is unambiguous. Municipal green-building requirements have tightened steadily, energy-performance benchmarking is expanding, and the national carbon-peaking deadline of 2030 sits inside the hold period of any asset acquired this year. Green finance channels — preferential lending for certified retrofits, and a deepening domestic green bond market — make the capital stack more forgiving than it was a decade ago.
For tenants, the pressure is coming from outside China as much as inside it. Chinese manufacturers exporting to Europe now face carbon border adjustment exposure, and building emissions enter the calculation through Scope 3. A landlord who can supply credible, metered building data is selling something a tenant genuinely needs.
Wellness Is the Retention Story
This is where the retrofit case stops being about carbon and starts being about people. Older towers frequently suffer from the same complaints: uneven ventilation, poor filtration during particulate season, acoustic leakage between floors, and lighting that predates any serious thinking about circadian comfort.
Remediating those four items delivers measurable tenant outcomes — fewer complaints, better attendance in dense-floorplate operations, and a workplace that a multinational can point to in its own reporting. WELL certification at the building scale is not decorative here; it is a leasing instrument. Retention compounds. In a market where incentives can consume months of rent, a two-point improvement in renewal rate is worth more than a headline chiller upgrade.
The Stranded-Asset Risk Nobody Prices
Here is the uncomfortable proposition: the greatest risk in Beijing prime office is not oversupply. It is the widening gap between buildings that can evidence performance and buildings that cannot. As disclosure norms tighten and corporate occupiers standardize their real estate requirements globally, the uncertified, unmetered, unimproved tower becomes progressively harder to lease at any rent.
That repricing has not fully happened. When it does, the owners who intervened early will own the assets that clear the market, and the owners who waited will discover that the discount they captured was not a discount at all.
How to Underwrite It Honestly
Five tests should precede any commitment.
Residual land term. Beijing commercial land is granted on fixed terms. A 1990s asset may have fewer years remaining than the retrofit payback period assumes. This single variable kills more deals than any other and is routinely glossed over.
Structural and services feasibility. Confirm riser capacity, plant room volume, and electrical headroom before the architect is retained.
Tenant roll and lease language. Green lease clauses, service-charge recoverability, and the right to pass through capital costs determine whether the retrofit accrues to the landlord or to the tenant.
Certification pathway. Choose the standard the tenant market actually recognizes, and budget for operational certification rather than design-stage plaques.
Operating partner quality. Retrofits fail on execution, not on thesis. A local partner with commissioning discipline is worth more than a favorable entry price.
What Would Break the Case
A sharper-than-expected downturn in multinational occupancy would compress rents faster than retrofit savings accumulate. A relaxation of disclosure requirements would remove the urgency. And a disorderly exit market would strand capital regardless of building quality — family offices can tolerate illiquidity, but not indefinite illiquidity.
None of those risks is negligible. They are, however, currently priced into the entry. That is more than can be said for the new-build premium, where the thesis is already in the rent.
This article reflects editorial opinion and is not investment advice.